
Sri Lanka’s success in drawing private money into renewable energy will hinge less on how much power it can generate and more on whether it can deliver bankable projects, credible contracts and predictable procurement, according to the International Finance Corporation (IFC).
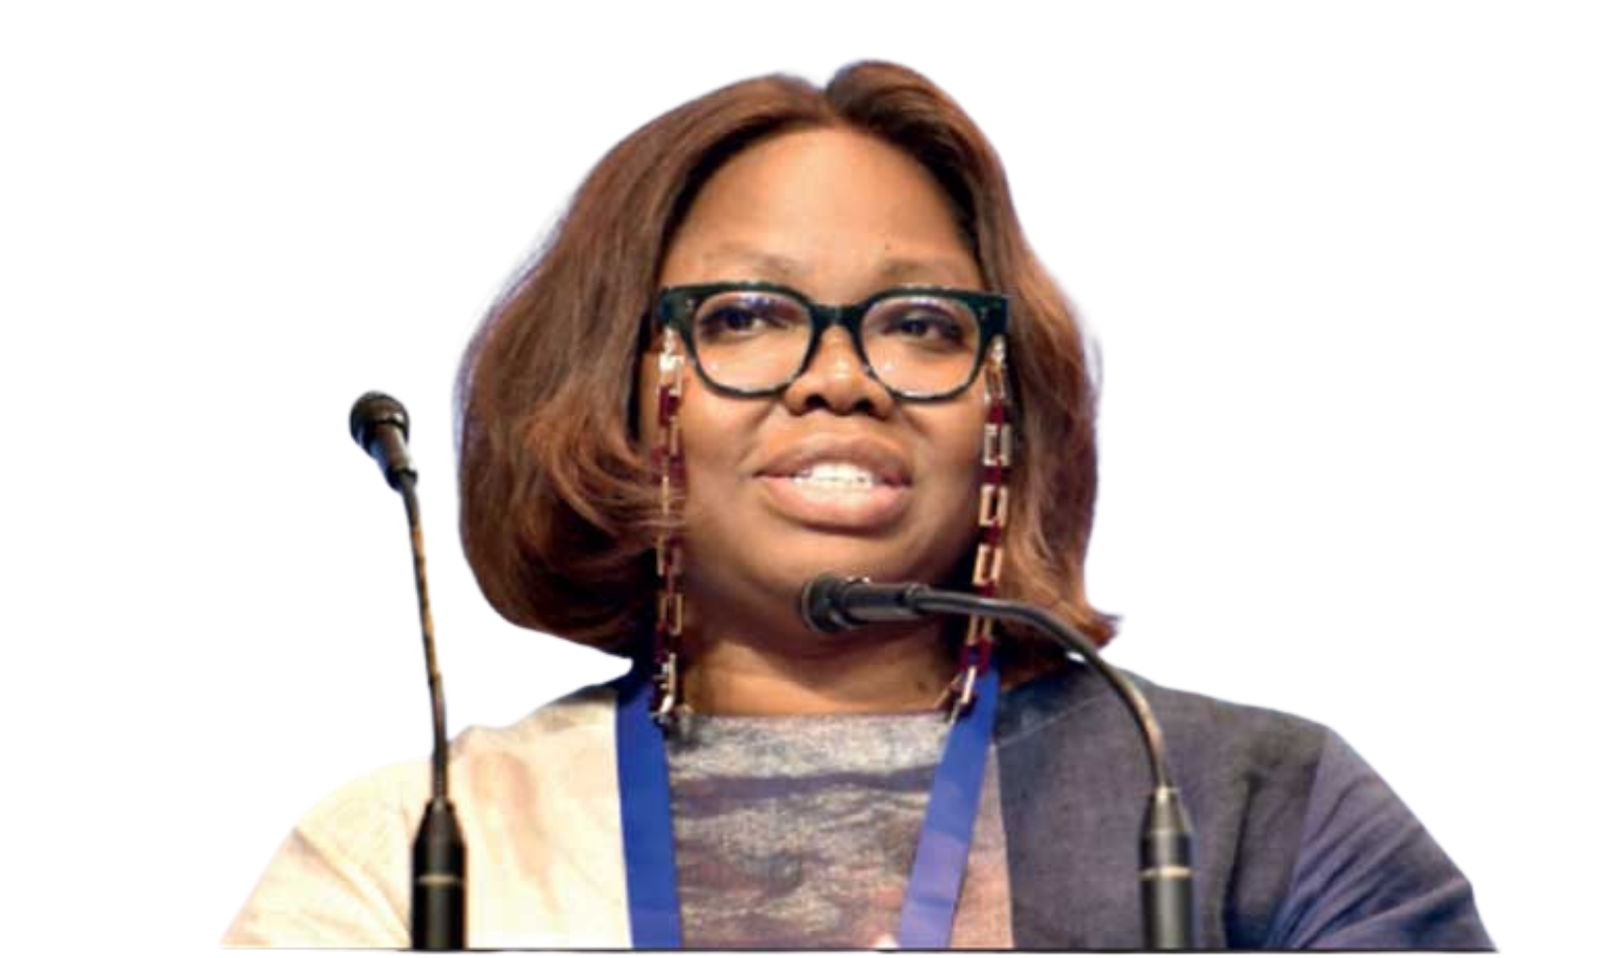
Speaking at the Sri Lanka Economic and Investment Summit 2026, IFC Regional Infrastructure Industry Manager for Bangladesh, Sri Lanka and Nepal Edore Onomakpome said the country starts from a position of strength. It has near-universal electricity access, a substantial hydropower base, relatively low network losses, and renewables supplying more than half of annual electricity generation.
Those advantages alone, however, will not attract investment at scale, she cautioned, particularly as the country seeks to integrate more wind and solar while keeping supply reliable and affordable.
“The success metric is not the number of entities being created, but whether each entity can plan, contract, recover costs and actually finance its investments,” she said, stressing the need to turn power-sector reforms into commercially credible institutions and projects that lenders can finance.
Lessons from the region
Comparing Sri Lanka with other Asian markets, Onomakpome said it performs reasonably well on access, hydropower and network efficiency but lags in the depth of procurement, financing structures and the pipeline of investment-ready projects.
Vietnam, she said, offers lessons in scaling renewables and coordinating transmission planning with generation growth. The Philippines shows the value of transparent competition, bankable contracts and a deeper private generation ecosystem, while Thailand offers examples of predictable procurement, established counterparties and stronger domestic financing. Sri Lanka should adapt these selectively rather than copy any one market. “It’s not a case of one size fits all,” she said.
What is holding investors back
Onomakpome named currency mismatches as a structural obstacle, especially where projects earn revenue in rupees but borrow in US dollars. Limited long-tenor rupee financing and the size of the domestic banking pool narrow funding options further, while investors can also weigh Sri Lanka against larger neighbours such as India.
Regulatory uncertainty, contractual risks and doubts over the financial strength of electricity purchasers can make project cash flows less predictable, pushing up borrowing costs and the returns equity investors demand.
She also pointed to a less visible constraint: poor project preparation. Land, environmental and social compliance, permits, grid interconnection and procurement arrangements must be settled before projects go to market. “We tender projects and then we struggle with actually having these projects financed,” she said.
Four priorities
Sri Lanka has made progress in changing its legal framework and unbundling the electricity sector, she said, but the reforms will be judged by how the new institutions perform. She identified four linked priorities: commercially credible institutions, transparent and competitive procurement, stronger grids and storage to handle variable renewable energy, and evolving market arrangements such as wheeling, open access and stronger corporate demand. Over time, interconnection and green electricity products could open opportunities beyond the domestic market.
Tools on offer
The World Bank Group has approved a program combining green investment, institutional strengthening and a payment-risk guarantee. The next test, she noted, is implementation, including credible contracts, appropriate tariffs, clear rules on curtailment and funded investment plans.
The Group’s toolkit includes project-preparation and advisory support, long-term financing, mobilisation of other lenders, local-currency and blended-finance solutions, political-risk insurance and guarantees. Payment guarantees can back defined public-sector payment obligations, while political-risk insurance can cover specified non-commercial risks.
She warned, though, that such instruments should not be used to paper over weaknesses in the underlying market. The priority should be to pick a small number of strategically important transactions, prepare them to standards investors trust, and apply risk protection only where the market cannot absorb the exposure efficiently.
“If we do that, the energy transition can move from security to competitiveness and possibly over time exports,” she said.